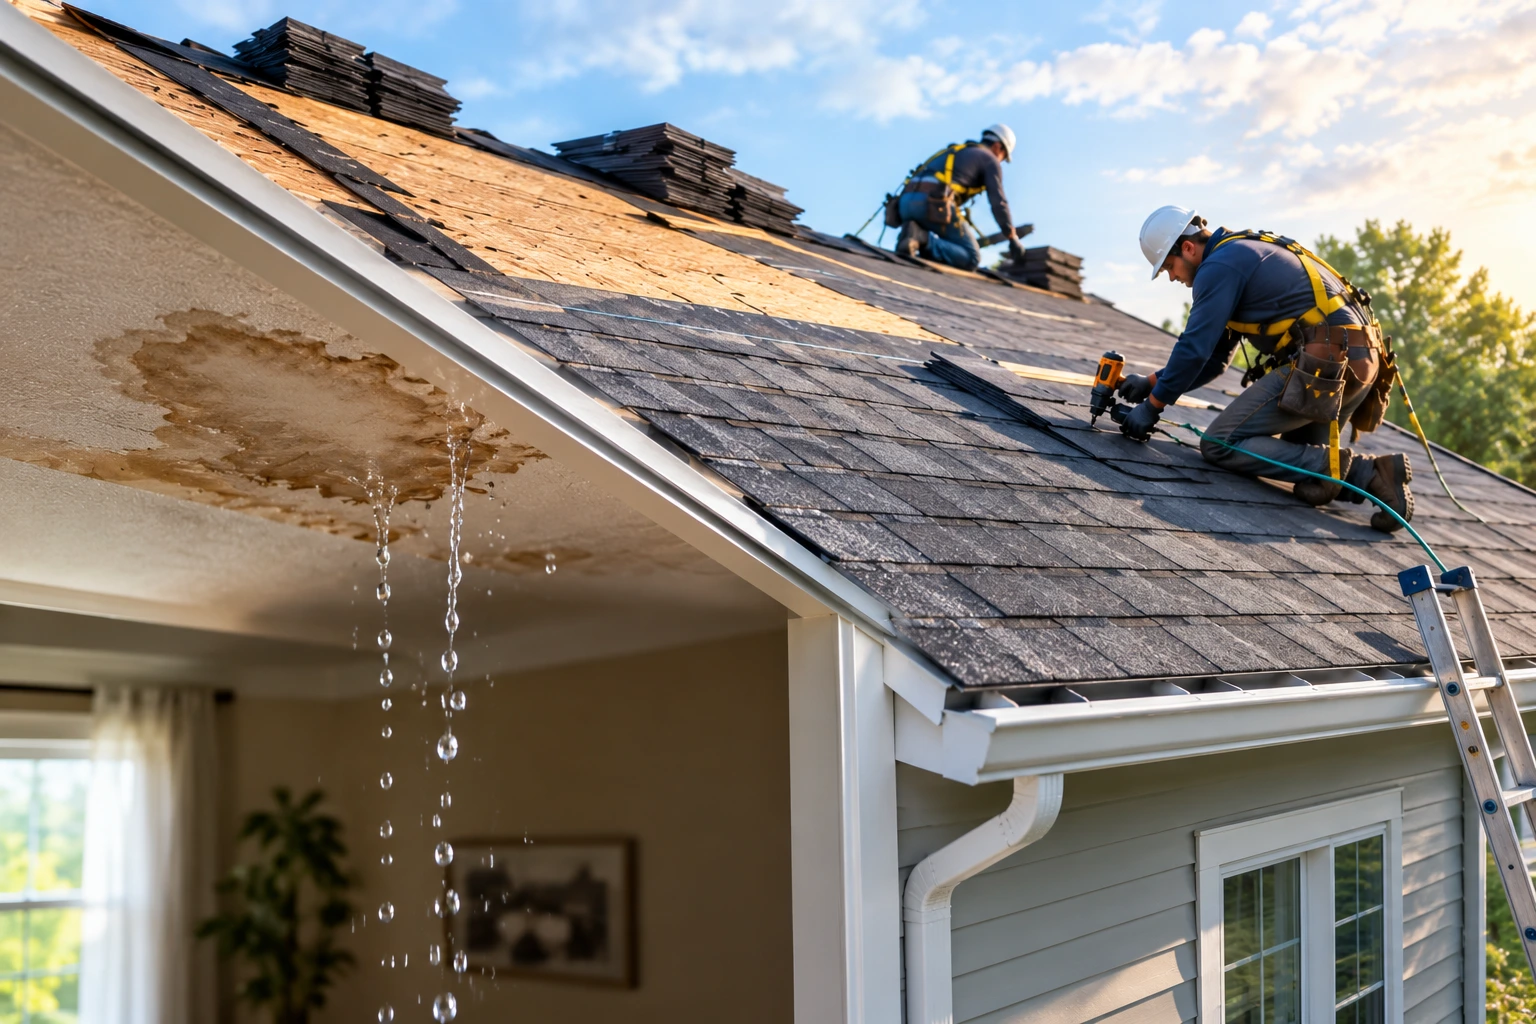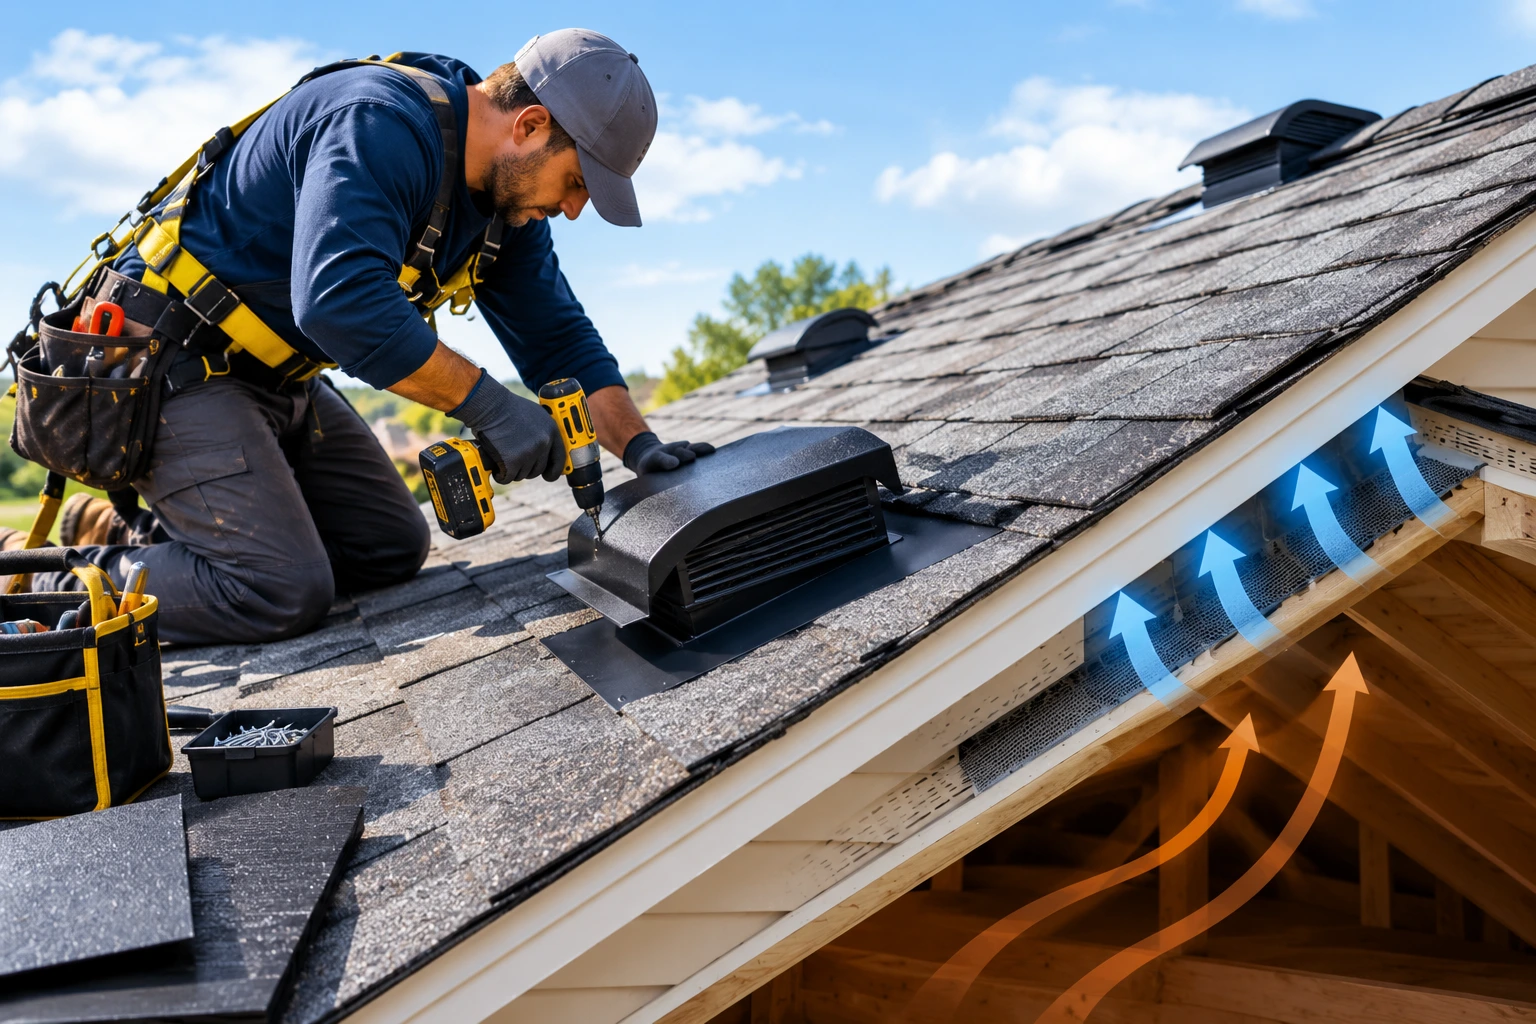
Filing an insurance claim after roof damage can be frustrating, when you expect your policy to cover a full roof replacement and receive a denial instead. You may assume that visible damage automatically qualifies for complete replacement, but insurance companies evaluate the cause, severity, age, condition, policy language, and documentation surrounding the roof. Thus, understanding Why did insurance deny my full roof replacement claim? can help you determine what went wrong and what steps may be available next.
What are the Reasons a Roof Replacement Claim Is Denied?
Insurance coverage depends on the specific terms of the policy and the cause of the damage. A claim may be denied when the insurer determines that the roof problem resulted from an excluded event, long-term deterioration, poor maintenance, or another condition not covered by the policy.
- Damage considered normal wear and tear
- Roof deterioration caused by age
- Previous unrepaired damage
- Insufficient evidence of a covered event
- Poor maintenance
- Damage below the policy deductible
- An excluded cause of loss
- Incomplete or inaccurate claim documentation
- The insurer determines that only part of the roof requires repair
What Qualifies a Roof for Full Insurance Replacement?
Many of you ask, What qualifies a roof for full insurance replacement? There is no single condition that automatically guarantees coverage.
- It depends on the insurance policy, applicable exclusions, the cause of damage, and the extent of covered damage.
- A roof may be considered for replacement when a covered event causes damage that is extensive enough that repairing individual areas is not sufficient to restore the roof.
- Significant storm damage, widespread wind damage, hail impacts, falling-object damage, or other covered losses may potentially result in a replacement decision.
- An older roof with substantial pre-existing deterioration may be evaluated differently from a relatively new roof that suddenly experiences severe storm damage.
- Photographs, inspection findings, repair estimates, maintenance records, and evidence showing when the damage occurred can help establish the circumstances surrounding a claim.
Does Roof Age Determine Insurance Replacement?
Another common question is, How old does a roof have to be for insurance to replace it? There is no universal age at which an insurance company must replace a roof.
- Some policies may treat older roofs differently from newer roofs, while certain policies may have specific limitations related to roof age, materials, depreciation, or settlement methods.
- The policy language should therefore be reviewed carefully before assuming that a roof’s age automatically qualifies or disqualifies a replacement.
- For instance, a roof that is several years old could still have covered storm damage, while an older roof may have substantial deterioration that is not considered a covered loss.
What is the Difference Between Damage and Wear?
One of the most important distinctions in a roof insurance claim is whether the problem resulted from a sudden covered event or gradual deterioration.
- Wind may lift or damage shingles during a storm, while hail can create impact marks and damage roofing materials.
- By contrast, cracked materials, general aging, loss of granules over time, or deterioration from prolonged exposure may be considered maintenance or wear-related issues.
- This distinction can affect whether an insurance company approves repairs, approves replacement, or denies the claim.
What to Do After a Roof Insurance Claim Is Denied?
A denial does not necessarily mean that you should immediately give up on the claim.
- Start by obtaining the written explanation for the denial.
- Review the stated reason and compare it with the relevant portions of your insurance policy.
- Next, consider getting an independent roof inspection.
- A qualified roofing professional can document visible damage and provide an estimate describing the required work.
Useful documentation may include:
- Photos of damaged roofing materials
- Videos showing storm-related conditions
- Roof inspection reports
- Repair or replacement estimates
- Previous maintenance records
- Information about the date of the suspected loss
- Weather or storm documentation when applicable
- The insurance company’s written denial
Can a Partial Repair Become a Full Replacement?
Sometimes you receive an estimate for limited repairs even though they believe the entire roof needs replacement.
- If a full replacement is appropriate depends on the extent and nature of the covered damage, the roof’s condition, applicable building requirements, and the insurance policy.
- If damage affects multiple roof sections or repairing individual areas would not adequately restore the roofing system, a broader scope of work may need to be evaluated.
- However, this should be supported by inspection findings rather than simply assuming that every damaged roof requires complete replacement.
Why Understanding Your Policy Before Filing is Essential?
You should review your policy before assuming that every type of roof damage is covered.
- Important details can include covered causes of loss, exclusions, deductibles, depreciation, roof-age provisions, settlement methods, and claim deadlines.
- If the policy language is difficult to understand, consider discussing it with an appropriately qualified insurance professional or legal adviser.
Frequently Asked Questions
Why might an insurance company deny a full roof replacement claim?
A claim may be denied because the insurer considers the damage normal wear and tear, aging, poor maintenance, pre-existing damage, an excluded cause, or insufficiently documented storm damage.
What evidence can support a roof replacement insurance claim?
Helpful evidence may include photographs and videos of the damage, professional inspection reports, repair estimates, maintenance records, and documentation showing when the suspected damage occurred.
What qualifies a roof for full insurance replacement?
A full replacement may be considered when a covered event causes extensive damage that cannot reasonably be addressed through isolated repairs. The final decision depends on the policy, damage assessment, exclusions, and applicable requirements.
How old does a roof have to be for insurance to replace it?
There is no universal roof age that automatically qualifies a roof for insurance replacement. Coverage can depend on the policy’s roof-age provisions, the roof’s condition, depreciation rules, and whether the damage resulted from a covered event.
What should I do if my roof insurance claim is denied?
Request the written explanation for the denial, review your policy, document the roof damage, and consider obtaining an independent professional inspection. If necessary, you can discuss the claim with a qualified insurance professional.